The 2026 hydrogen market update shows a sector entering a more disciplined phase. Capital is still moving into projects, operating capacity is rising, and China remains the center of electrolyser deployment. At the same time, weaker projects are being delayed or cancelled, firm demand remains limited, and buyers are asking harder questions about cost, evidence, and execution.
For hydrogen water brands, distributors, and OEM buyers, the signal is not that an industrial hydrogen boom automatically creates demand for portable hydrogen products. Industrial low-emissions hydrogen and hydrogen water are distinct markets. The useful connection is behavioral: across both markets, the conversation is moving from ambitious claims to verifiable performance, bankable demand, and repeatable delivery.
2026 Hydrogen Market Update: Key Snapshot
| Signal | Latest indicator | Why it matters |
|---|---|---|
| Committed clean-hydrogen investment | USD 130 billion across 579 projects | More projects are moving beyond announcements |
| Committed clean-hydrogen capacity | 6.9 Mtpa, with 1.7 Mtpa operational | Execution is becoming visible, but scale remains concentrated |
| Global hydrogen demand in 2025 | More than 100 Mt | Almost all demand still comes from established industrial uses |
| Low-emissions hydrogen production in 2025 | Almost 1 Mt | Growth is fast from a small base |
| Installed electrolysis capacity | More than 4 GW after doubling in 2025 | China supplied nearly three-quarters of new installations |
| New low-emissions hydrogen offtake in 2025 | About 1.7 Mtpa; only one-fifth firm | Demand certainty remains the main bottleneck |
1. The Market Is Moving From Announcements to Execution
The Hydrogen Council’s Global Hydrogen Compass 2026 counts USD 130 billion in committed clean-hydrogen investment across 579 projects, representing 6.9 million tonnes per year of capacity. It reports that 1.7 Mtpa is already operational and that operational capacity grew 70% over the previous year.
The IEA’s Global Hydrogen Review 2026 presents the other side of the same transition. The announced low-emissions hydrogen pipeline for 2030 fell to 27 Mt as projects were delayed, paused, or cancelled. New final investment decisions slowed in 2025, and 22 Mt of potential production could miss a 2030 start if investment decisions are not taken by early 2027.
These figures are not contradictory. They reflect different definitions and show a market being filtered: credible projects are advancing while weaker assumptions are being removed from the pipeline.
What this means for hydrogen water buyers
Procurement is following the same pattern. A catalog listing, a high concentration number, or an attractive render is only an announcement. Buyers increasingly want the equivalent of execution evidence: a physical sample, a documented test method, configuration-specific reports, an approved packaging file, a quality-control plan, and a repeat-order reference.
2. Demand Certainty, Not Technical Possibility, Is the Constraint
Global hydrogen demand exceeded 100 Mt in 2025, but the IEA reports that almost all of it remained in traditional applications such as refining and chemicals. Low-emissions hydrogen demand reached almost 1 Mt. New offtake agreements covered about 1.7 Mtpa, broadly unchanged from 2024, and only around 20% of newly signed volume was backed by firm commitments.
The lesson is commercial rather than technological: a product can work and still fail to create reliable demand. For a hydrogen water brand, a launch plan should identify the buyer, channel, acceptable price band, evidence required by the channel, after-sales model, and realistic reorder trigger before a large production commitment.
- Distributor channel: prioritize documentation, margin structure, spare parts, training, and territory clarity.
- E-commerce channel: prioritize claim control, content assets, packaging durability, returns, and replacement handling.
- Wellness or professional channel: prioritize operating instructions, cleaning procedures, repeatability, and evidence boundaries.
3. China Leads Electrolysis Deployment, but Product-Level Verification Still Matters
According to the IEA, global installed water-electrolysis capacity doubled in 2025 to exceed 4 GW, with China accounting for nearly three-quarters of new installations. China also benefits from accumulated project experience, a broad component ecosystem, and strong cost competition.
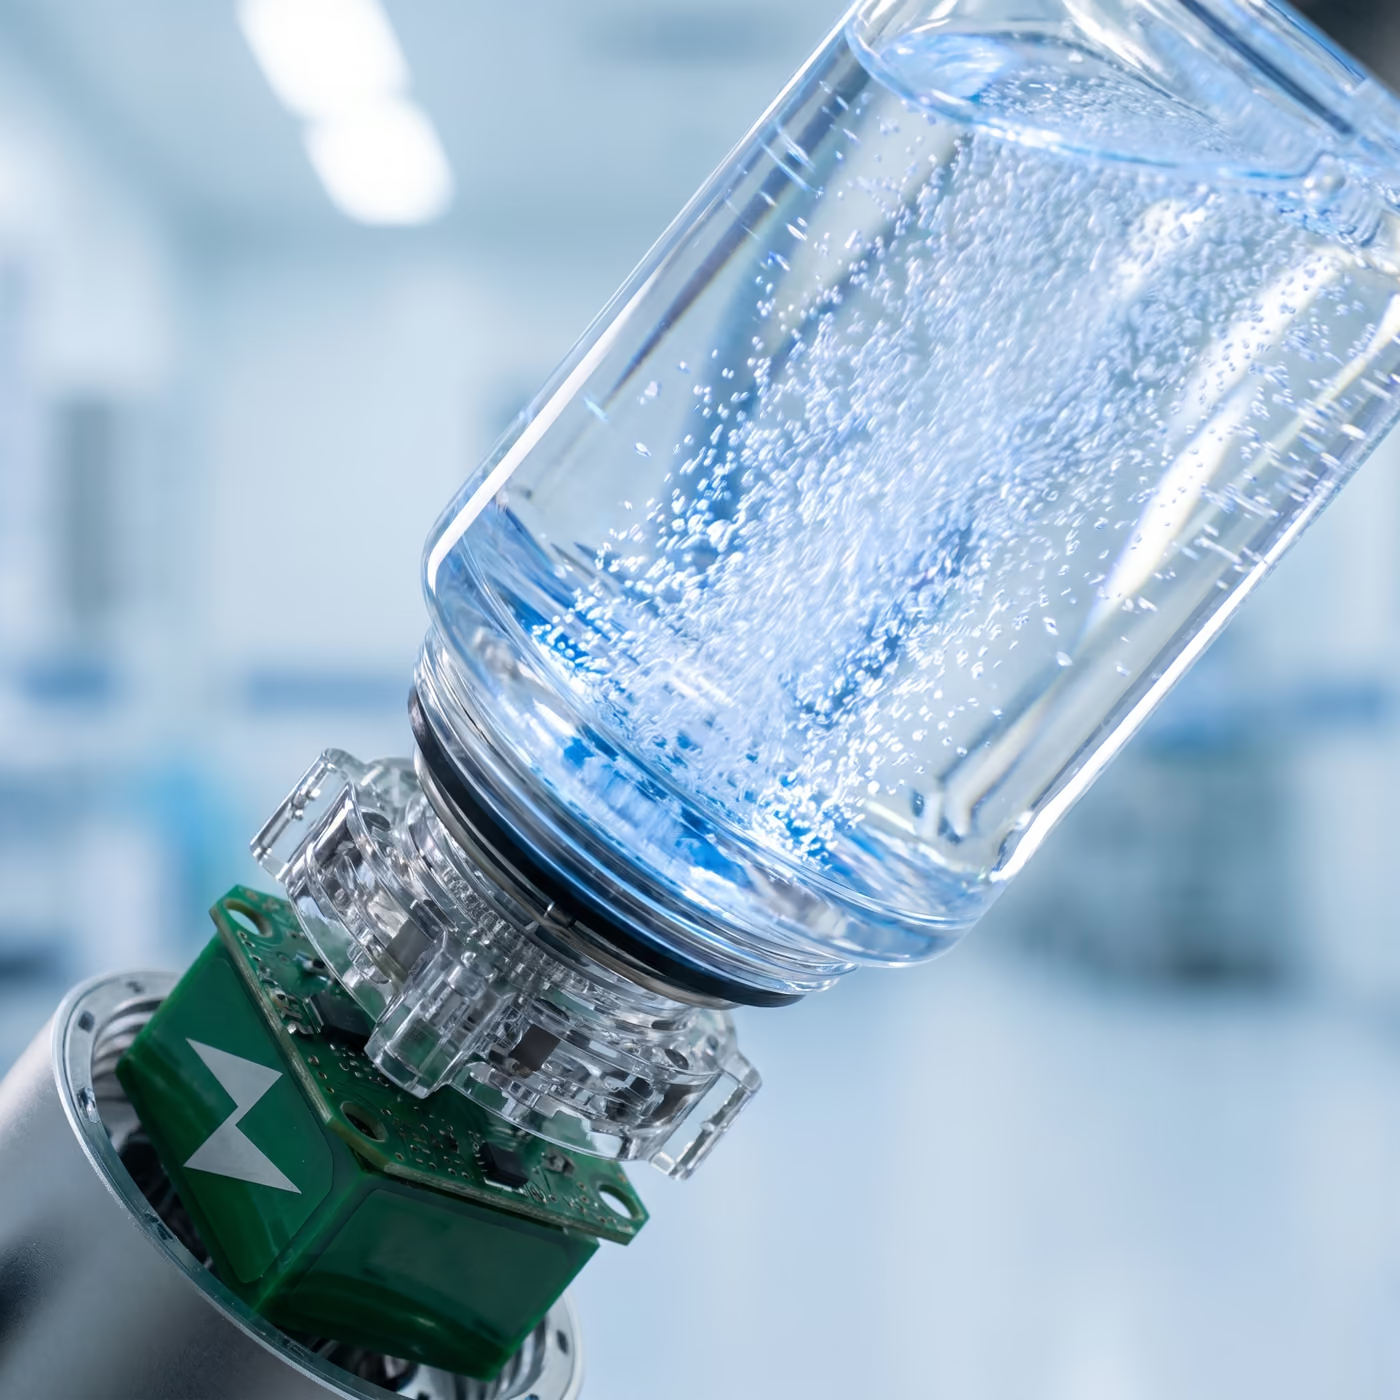
Industrial electrolysers are not the same as the compact SPE/PEM assemblies used in hydrogen water bottles. Scale, duty cycle, pressure, water path, gas handling, electronics, and end-use requirements differ. A country’s strength in industrial electrolysis therefore does not prove the performance of a specific portable product.
For buyers, the practical advantage of a mature supplier ecosystem appears only when it is converted into product controls. Ask which membrane-electrode assembly is used, how incoming components are inspected, whether gas separation matches the product design, what water and cycle conditions were used in testing, and how component changes are approved.
PHYFLOW’s guide to SPE/PEM hydrogen bottle systems provides a model-level framework for sample tests and supplier questions.
4. Policy Support Is Becoming More Targeted and Measurable
Governments are still supporting hydrogen, but the mechanisms increasingly reward measurable output rather than broad ambition. The European Hydrogen Bank’s 2025 auction, completed in 2026, selected projects expected to install almost 1.1 GW of electrolyser capacity and produce more than 1.4 million tonnes of hydrogen over their first ten years. Funding is linked to verified and certified production.
That policy design points to a wider market expectation: claims need defined conditions and records. Hydrogen water products operate under consumer-product, electrical, battery, food-contact, labeling, and advertising rules rather than industrial hydrogen policy. The exact obligations depend on product configuration and destination market.
Importers should therefore build a model-specific file instead of asking whether a factory is “certified” in general. The file may need product specifications, material information, electrical or EMC records, battery transport documents, label artwork, instructions, and claim review. Our packaging, battery shipping, and UN 38.3 checklist explains how to organize part of that review.
5. The Hydrogen Water Market Is Entering an Evidence-Led Buying Cycle
There is no authoritative public dataset that allows industrial hydrogen investment to be converted into a reliable global market-size estimate for hydrogen water bottles. Treating the two as one market would be misleading.
What can be observed in B2B sourcing is a change in buyer behavior. Serious importers are moving beyond a single headline specification and evaluating the complete product program:
- hydrogen concentration under a documented water type, temperature, cycle time, fill volume, sampling delay, and test method;
- consistency across repeated cycles and multiple samples, not only the highest result;
- membrane, electrode, seal, bottle, and water-contact material choices;
- battery identification, charging behavior, and transport documentation;
- cleaning instructions, leakage checks, fault handling, and after-sales parts;
- logo, color, packaging, manual, and accessory control for the approved SKU; and
- change notification and retained reference samples for repeat orders.
Overall, this 2026 hydrogen market update favors suppliers that can explain trade-offs, reproduce an approved configuration, and provide records tied to the product being ordered. It also favors brands that define a narrow, supportable offer rather than relying on unqualified wellness claims.
What to Expect Through 2027
- More filtering of suppliers and projects. Cost pressure will continue, but buyers will place more value on traceability, change control, and repeatability.
- More specific test language. Concentration claims without conditions will become less useful for professional procurement.
- More market-specific documentation. A single generic certificate package will not answer every EU, US, or other destination-market question.
- More platform-based private label programs. Established product platforms with controlled options can shorten sampling and reduce avoidable tooling risk.
- More evidence-led content. Brands will need clear boundaries between product operation, measured performance, and health-related claims.
A Practical 2026 Sourcing Checklist
- Define the destination market, sales channel, target quantity, and launch timing.
- Request the exact model and configuration behind every test document.
- Compare hydrogen results only when test conditions are documented.
- Approve a physical sample and retain a reference for production.
- Confirm materials, battery, accessories, packaging, and manuals as one controlled SKU.
- Define incoming, in-process, functional, leakage, cosmetic, and packing checks.
- Agree how component or document changes will be communicated before repeat orders.
Use our hydrogen water bottle RFQ template to turn these points into a comparable supplier brief.
Frequently Asked Questions
Is the hydrogen market growing in 2026?
Committed clean-hydrogen investment and operating capacity are growing, but announced project pipelines are also being reduced as weaker projects are delayed or cancelled. The most accurate description is maturation rather than uninterrupted expansion.
Does clean-hydrogen investment measure demand for hydrogen water bottles?
No. Industrial hydrogen and hydrogen water products have different customers, technologies, regulations, and economics. Macro hydrogen data provides context about technology investment and market discipline, not a direct market-size estimate for bottles.
What should a buyer verify on an SPE/PEM hydrogen water bottle?
Verify the exact product configuration, electrolysis architecture, test conditions, repeated-sample results, water-contact materials, battery information, cleaning instructions, model-specific documents, and production quality plan.
What is the biggest commercial risk in a private-label hydrogen bottle project?
A common risk is approving marketing before the physical product, test method, documents, packaging, and after-sales process are controlled as one SKU. Resolve those dependencies before scaling the order.
Plan a Verifiable Hydrogen Water Product Program
PHYFLOW works with distributors, importers, and private-label brands on model review, SPE/PEM configuration, samples, branding, packaging, documentation, and production quality controls. Contact the PHYFLOW B2B team with your target market, product direction, quantity, and launch requirements.
Sources and scope: Market figures are drawn from the IEA Global Hydrogen Review 2026, Hydrogen Council Global Hydrogen Compass 2026, and European Commission European Hydrogen Bank materials available in October 2026. Industrial hydrogen data is used as macro context and is not presented as a market-size estimate for hydrogen water products.